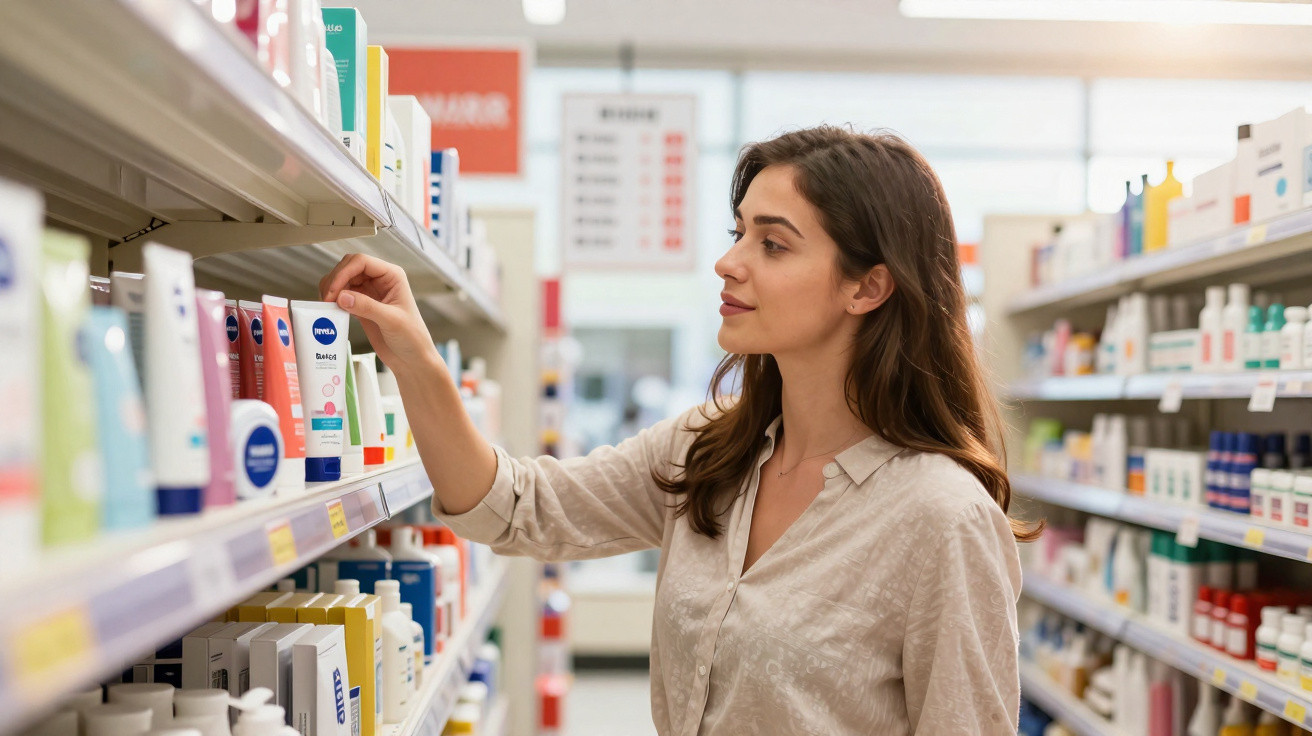
In the latest customer satisfaction rankings, Nivea has slipped from the top spot. The surprise is that it has not been overtaken by a luxury brand, but by Balea, the own-brand range of the dm chemist chain. What may appear to be a minor detail points to a profound shift in shopping habits – and shows just how powerful retailer brands have become.
Traditional brand under pressure: how the ranking has changed
The new customer satisfaction favourite comes from a shelf long dismissed as the “cheap alternative”. In the YouGov BrandIndex, Balea now records a net score of 65.3 points, compared with 61.8 points for Nivea.
Balea is clearly ahead of Nivea in customer satisfaction – a genuine turning point in the mass-market skincare sector.
The finding becomes even more striking when viewed historically. In 2021, the situation was reversed: Nivea held a 1.6-point lead over Balea. Within only a few years, the relationship has changed completely. For a long-established brand associated for decades with dependability, family familiarity and “the white tin in the cupboard”, this is more than a statistical fluctuation.
Why the new number one sends such a strong signal
Nivea remains one of the country’s best-known brands, yet the momentum is shifting. In market research, satisfaction is considered a key driver of loyalty: people who are highly satisfied with a brand are less likely to choose alternatives and more inclined to recommend it.
Balea is now gaining ground precisely in this area. It is no longer viewed merely as “cheap but fine”, but increasingly as a genuine favourite brand. Many shoppers deliberately choose Balea, not because they have no money to spare, but because they are convinced by it.
- Brand image: modern, suited to everyday life, with an eye-catching range
- Price perception: fairly priced rather than “cheap at any cost”
- Accessibility: available nationwide in dm stores and clearly positioned on shelves
- Range breadth: from basic creams to trend-led products such as serums and sheet masks
This means a retailer brand is encroaching on an area that was long regarded as the preserve of established manufacturers: mass-market bodycare and facial skincare.
Value for money: arguably the most important factor in Balea versus Nivea
One major reason for Balea’s rise is its value for money. This is also where the BrandIndex scores diverge most clearly. According to the data, Balea currently achieves 42.7 points, while Nivea reaches 31.1 points.
In perceptions of value for money, Balea is now well ahead of Nivea – and continues to widen the gap.
Importantly, this measure does not simply mean “cheap”. Respondents assess whether the value they feel they receive matches the price. Many therefore see Balea as not only less expensive, but as a “sensible deal” – a cream that appears worth its price.
At a time when food, rent and energy costs are rising, many households are taking a sharper look at their spending: where is a brand premium genuinely worthwhile, and where will a chemist own brand do the job? When it comes to skincare creams, the answer increasingly appears to favour Balea.
Still strong: where Nivea remains ahead
Losing its place at the top does not mean that Nivea has suddenly become a problematic product. On the contrary, Nivea still stands clearly above Balea in the “perceived quality” category. For 2025, the BrandIndex gives Nivea 55.0 points and Balea 42.5 points.
Many people therefore still place greater trust in Nivea’s technical performance and quality. The brand benefits from decades of product development, dermatological research and a global presence. At the same time, the figures show that an advantage in quality alone does not automatically secure a lead in satisfaction and value for money.
There is also no doubt about the strength of the established brand when it comes to awareness:
| Criterion | Nivea | Balea |
|---|---|---|
| Brand awareness | 92.1% | 76.9% |
| Purchase intention among people aware of the brand | 21.0% | 23.3% |
Perhaps the most interesting figure appears in the final row: among people familiar with both brands, Balea is narrowly ahead of Nivea for intended purchases. This illustrates how effectively the chemist brand is mobilising its fans, despite its lower overall awareness.
How the YouGov BrandIndex works – and what it measures
The BrandIndex is not a conventional laboratory test such as those carried out by Stiftung Warentest. YouGov continually surveys thousands of people online about how they perceive different brands. Their responses create ongoing time series.
The measures include:
- overall impression
- perceived quality
- customer satisfaction
- willingness to recommend
- value for money
- employer image
According to the institute, more than 900,000 interviews were included in the analysis for a current value-for-money ranking. The figures therefore do not represent a brief snapshot following a viral online backlash, but a longer-term picture of public opinion.
Even so, one point remains crucial: these scores reflect subjective perceptions, not objective product quality. A cream may perform extremely well in laboratory testing yet lose out in people’s minds if, for example, its price is seen as too high or its packaging looks old-fashioned.
Where Nivea continues to perform well – and where its problems lie
Nivea is not losing ground across the board. In rankings of general popularity, Handelsblatt reports that the brand scores around 89 points, only just behind Florena. This means its underlying appeal remains very high, and the brand is still present in everyday life – both in advertising breaks and in bathroom cabinets.
The issue is more about momentum: while cheaper or newly repositioned brands are making substantial gains, Nivea tends to be standing still. Inflation, higher living costs and changing price awareness hit brands with a premium particularly hard.
Nivea’s real weakness is not rejection, but the fact that other brands are gaining popularity more quickly.
There is also a trend retailers have observed for years: own brands are no longer simply “no name” products, but are building identities of their own through social-media campaigns, limited editions and clear stories around sustainability or skin compatibility.
What shoppers can take from the ranking in everyday life
When standing in front of the shelf, consumers face a simple question: is it still worth choosing the more expensive traditional brand, or will the cheaper own brand be enough? The answer is becoming increasingly personal, depending on skin type, budget and individual preferences.
It is worth looking more closely during the next shop:
- Compare ingredients: Many own brands base their formulas on well-known branded products.
- Check the price per 100 ml: Only a comparison by standard unit reveals how large the difference really is.
- Try it in practice: Test a tin or tube of Balea and see how it feels on the skin and how well it is tolerated.
- Choose a mix of brands: Use Nivea or dermatological brands for sensitive facial skin, and more affordable alternatives for body lotion – this is how many households save in a targeted way.
Those who value long-standing research, particular fragrances or a familiar brand image may continue to choose the blue tin. Those more focused on their budget and willing to experiment with cosmetics will often end up with Balea & Co.
Own brands on the rise: what this means for the market
Balea’s success demonstrates a fundamental retail trend: the line between “branded product” and “own brand” is becoming blurred. Discounters and chemist chains are investing heavily in the design, development and marketing of their own ranges. What was once a “no name” product is becoming a label with clear recognition value.
For manufacturers such as Beiersdorf, the company behind Nivea, this means traditional strengths such as decades of history and brand awareness are no longer enough on their own. Pricing strategy, speed of innovation and clear differentiation are becoming more important. Otherwise, even iconic brands risk falling behind on core measures such as satisfaction and value for money.
For consumers, however, this development is often positive: stronger competition generally results in keener prices and a wider choice. Anyone who takes a little time to compare ingredients and prices can make noticeable savings without necessarily compromising on care.
Comments
No comments yet. Be the first to comment!
Leave a Comment